For telecom operators building a network API business, one question comes up quickly:
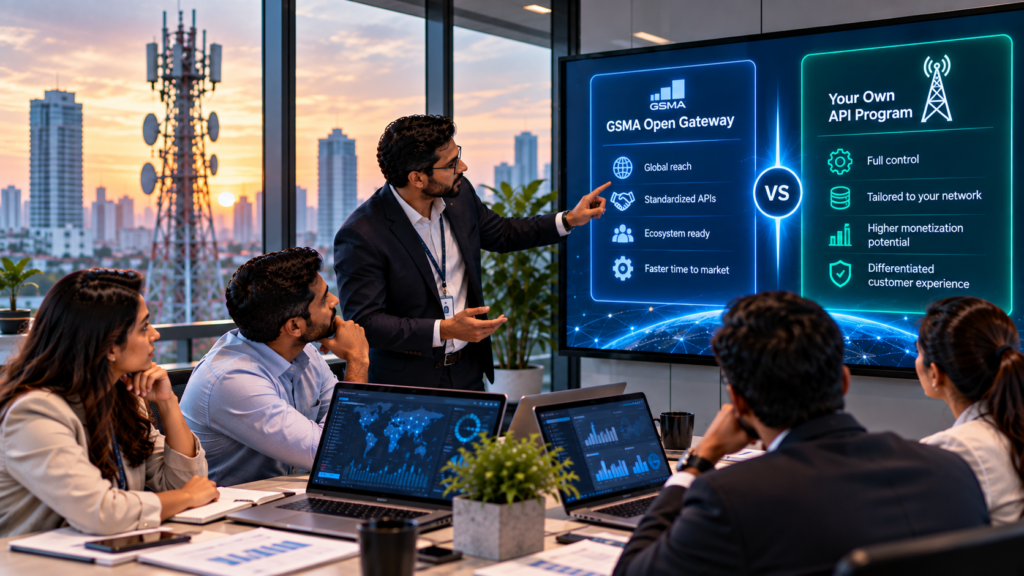
Should we align with GSMA Open Gateway, or build and commercialize our own API program?
The useful answer is not automatically one or the other.
GSMA’s own technical guidance supports aggregation, federation and direct-integration models. An operator can standardize APIs around Open Gateway and CAMARA while still deciding how it sells, packages and operates those APIs.
So the real decision is about four things: reach, speed, commercial control and the customer relationship.
First, understand what Open Gateway actually gives you
GSMA Open Gateway is a common framework for exposing network capabilities through standardized APIs.
Instead of developers integrating differently with every operator, capabilities such as identity verification, location and quality of service can be exposed through common interfaces based on CAMARA specifications.
The scale is already significant.
As of March 2026, 86 operator groups covering more than 300 networks and roughly 80% of global mobile connections were aligned around the framework. More than 60 channel partners, including CPaaS providers, aggregators and hyperscalers, were commercializing network APIs.
That reach is difficult for one operator to reproduce alone.
When reach matters most, Open Gateway has an advantage
Imagine a bank wants to deploy the same Number Verification capability across customers using five different mobile networks.
If every operator exposes a different proprietary API, the bank or its technology provider has to integrate each one.
Open Gateway is designed to reduce that problem.
In the aggregation model, a channel partner can combine standardized CAMARA APIs from multiple operators and provide developers with one operator-agnostic interface. GSMA specifically identifies this as a way for operators to reach developers that may not want individual integrations with every network.
For APIs where value increases with cross-operator coverage, that can be a major advantage.
Where an operator-owned program gives you more control
Reach is not the only consideration.
Running your own API program gives an operator more direct control over how capabilities are packaged and sold.
You can decide which enterprise segments to target, how APIs are bundled, what onboarding experience partners receive and how commercial offers are structured.
That can matter when the operator already has strong enterprise relationships or wants to create products specific to its market.
It can also make experimentation easier.
You might combine SMS, charging, authentication or location capabilities into a local enterprise package rather than waiting for the market to converge around a standardized product.
Our own AI CPaaS approach is built around this platform model. Telecom capabilities including SMS, OTP, charging, USSD, IVR, voice and location can be exposed through a common layer instead of creating a separate integration for every partner.
Do not assume Open Gateway decides your revenue model
This distinction is important.
Open Gateway standardizes how network capabilities can be exposed and consumed. It does not mean every operator must use one universal commercial agreement or revenue-share percentage.
Commercial relationships between operators, channel partners and application providers still need to be defined.
GSMA’s own channel-partner guidance treats the commercial model, contractual framework and integration model as areas where operators and partners need alignment.
In 2026, GSMA has also highlighted revenue sharing, per-feature pricing, outcome-based contracts and industry-specific packaging as commercial models the ecosystem needs to develop further.
So compare the economics carefully.
If a channel partner can bring significant additional volume, sharing part of the revenue may make sense.
If your operator already owns the enterprise relationship and distribution channel, selling directly may produce different economics.
The answer depends on the API and the route to market.
Compare time to market differently too
Building everything internally sounds like more control, but control has a cost.
You need API exposure, authentication, consent, onboarding, product catalogues, usage measurement, charging, billing, documentation, partner management and support.
Open Gateway is increasingly standardizing parts of this operational layer too. GSMA’s Operate API work covers areas such as application-provider onboarding, product ordering, service catalogues and usage information.
Using established standards can therefore reduce how much needs to be designed from scratch.
But if an operator already has those systems, an existing developer ecosystem and enterprise sales channels, its own platform may already provide a fast route to market.
That is why the starting point matters.
One lesson from operating at telecom scale
Across hSenid Mobile systems, nearly 50 million transactions are handled daily.
At that scale, we have learned that exposing an endpoint is the easy part.
The harder questions come immediately after:
Who can access it?
How are they onboarded?
How is every call measured?
What happens when consumption increases?
How is the operator paid?
How does the next partner integrate without creating another custom project?
Those questions matter whether the API is sold through Open Gateway, directly by the operator or through both routes.
The practical answer may be both
Operators do not necessarily need to choose between Open Gateway and an independent API business.
A stronger model can be:
Use CAMARA-aligned APIs where interoperability and cross-operator reach matter.
Use channel partners or aggregators where they provide access to developer and enterprise markets you cannot reach efficiently yourself.
Keep direct channels where your operator already owns the customer relationship or wants greater control over packaging.
Use a CPaaS platform underneath both to handle exposure, onboarding, monetization and scale.
That is also consistent with the direction of Open Gateway itself. The framework supports multiple commercialization and deployment models rather than forcing every operator through one route.
The decision is therefore not “Open Gateway or our own APIs?”
It is:
Which capabilities should be standardized for reach, which should we commercialize directly, and what platform lets us support both without rebuilding the network integration each time?
That is the architecture of a network API business, not just an API catalogue.